Can I Sell My House If I Owe More Than It's Worth in Virginia?
By Virginia Cash Real Estate ·
Yes, you can sometimes sell a house in Virginia when you owe more than it is worth, but the debt must be addressed before the sale can close. You may need to bring money to closing or obtain a lender-approved short sale. A cash buyer cannot simply eliminate your mortgage balance. Start with an accurate payoff statement and a realistic sale estimate, then compare selling with options that could let you keep the home.
This guide focuses on the funding gap—not just choosing a fast buyer. If missed payments are part of the problem, our foreclosure help page explains the related situation.
What negative equity means
Negative equity means the property's current value is below the debt secured against it. Homeowners also call this being underwater or upside down. You can be underwater while making every payment on time. Conversely, being behind on payments does not necessarily mean you have negative equity.
There is another important distinction: a home can have positive equity but still leave too little money to cover selling expenses. A $250,000 sale with a $245,000 payoff leaves $5,000 before commissions, settlement charges, or other obligations. That is not automatically $5,000 you can take home.
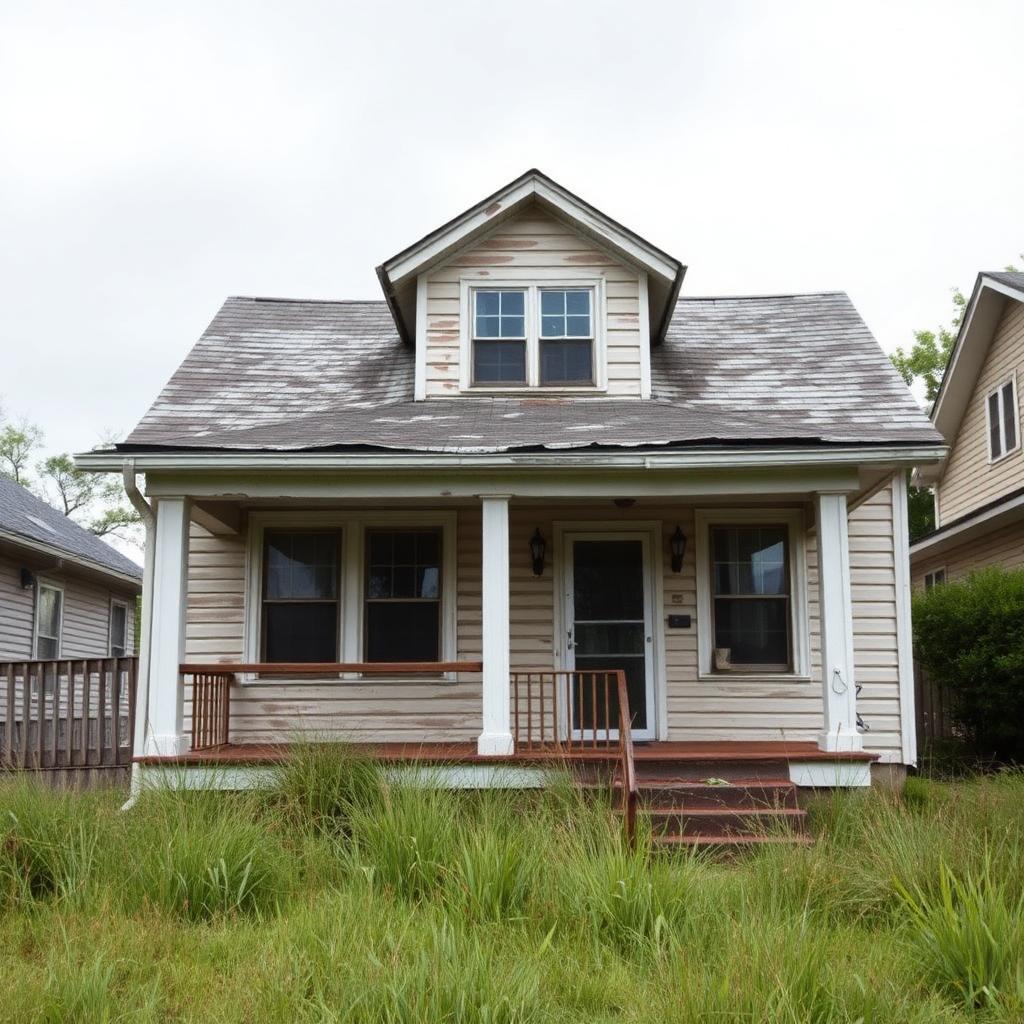
Do not compare the mortgage balance with a renovated neighbor's sale price. A Hampton Roads house needing a roof or substantial repairs may sell for less than an otherwise similar updated home. Use its current condition when estimating value.
Get the payoff and property value separately
Ask for a dated mortgage payoff statement
Your monthly statement balance is not necessarily the amount required to satisfy the loan on a particular closing date. Request a payoff statement from the servicer and ask what it includes. Accrued interest, applicable fees, and the payoff's expiration date matter. If closing changes, the settlement professional may need an updated figure.
Gather statements for a second mortgage or home-equity line as well. Tell the settlement professional about unpaid property taxes, judgments, or other known liens. Do not assume that one mortgage payoff answers every title question.
Estimate an achievable sale price
Ask a local agent for comparable sales and an estimate based on the home's present condition. Obtain written cash offers if you want that alternative. An online estimate is a starting point, not an appraisal, a purchase offer, or proof that a lender will accept less than it is owed.
Ask how each estimate handles needed repairs, concessions, and selling expenses. Our as-is selling guide provides broader context about selling a property without renovating first.
Calculate the shortfall before signing
Use this planning equation:
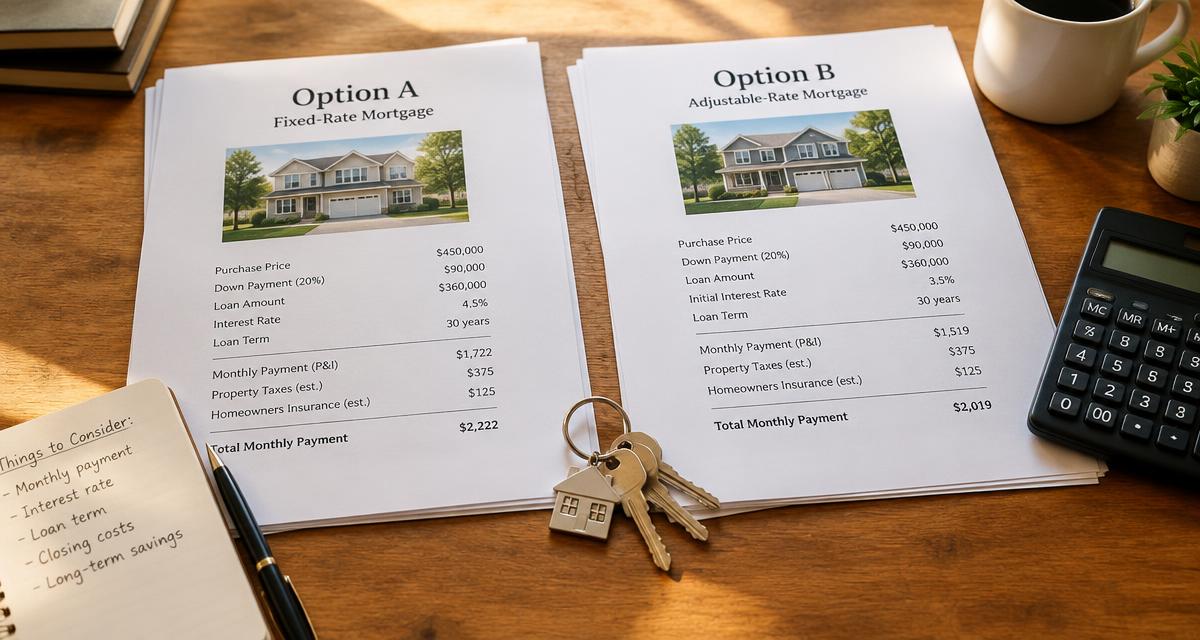
Estimated sale price − mortgage payoff − other required lien payoffs − seller expenses = estimated surplus or funding gap.
Hypothetical example—not a VCRE transaction: assume an as-is sale price of $225,000, a mortgage payoff of $238,000, and $4,000 in seller expenses. With no other liens, the funding gap is $17,000. Eliminating $2,000 of expenses would reduce the gap to $15,000, not make the mortgage disappear.
A second hypothetical home sells for $250,000 with a $244,000 payoff and $8,000 in expenses. The property has $6,000 of equity before selling costs, yet the seller still needs $2,000 to complete that assumed transaction. Both examples are estimates; actual payoff requirements and negotiated costs control.
Three ways a sale might work
| Path | What must happen | Main consideration |
|---|---|---|
| Sale with seller funds | Buyer proceeds plus your funds cover required payoffs and expenses | Whether you can safely afford the contribution |
| Lender-approved short sale | Relevant creditors agree to the proposed reduced payoff and lien release | Written approval, conditions, and remaining debt |
| Higher achievable sale price | An actual buyer pays enough to cover the obligations | Condition, time, costs, and whether the price is realistic |
A higher asking price alone is not a solution. Neither is accepting an offer that cannot satisfy the closing requirements. Have an agent, settlement professional, or attorney explain the proposed route before making a commitment.
Ready to Sell Your Hampton Roads Home Fast?
Virginia Cash Real Estate buys houses across Hampton Roads for cash — no repairs, no fees, no commissions. Get a fair cash offer within 24 hours.
Short sales require creditor approval
The CFPB defines a short sale as selling the home for less than the mortgage debt with the lender or servicer's agreement. Contact your servicer to ask about its application, documents, valuation review, and approval conditions. Requirements depend on the loan and creditor; approval is not guaranteed.
A lender may ask for financial records, information about your hardship, and a purchase offer. Multiple secured debts can complicate the process because the sale may require more than one creditor's cooperation. Ask who will coordinate those approvals and whether the offer allows enough time for review.
Our short sale versus cash sale comparison explains the two concepts. They are not mutually exclusive: a cash buyer can be the purchaser in a short sale, but the lender-approval requirement remains.
A lien release is not necessarily a debt waiver
The mortgage lien is the creditor's security interest in the property. Your obligation to repay the loan is a separate issue. Permission to transfer the property should not be treated as proof that every unpaid dollar has been forgiven.
The CFPB cautions that a borrower may remain responsible for a deficiency and recommends asking for a waiver in writing. Before closing, have a Virginia attorney review whether the approval addresses remaining debt, additional contributions, and any continuing obligations. Do not rely on a buyer's verbal assurance that you can walk away owing nothing.
Tax treatment is another separate question. Ask a qualified tax adviser about your circumstances rather than assuming that a lender's approval means there are no tax consequences. This guide does not establish deficiency liability or tax treatment for a particular Virginia loan.
What a cash buyer can—and cannot—do
A cash buyer may consider a house in poor condition without needing a buyer's mortgage. That can broaden the available offers, especially when repairs would make a financed purchase difficult. It does not give the buyer authority over your lender's payoff demand.
Compare the actual cash price with a realistic listing estimate after expenses. Saving commissions or repair spending can help the calculation, but a lower cash price can also leave a larger funding gap. Cash is not inherently the best answer for an underwater owner.
If a proposed transaction leaves your existing loan in place rather than paying it off, do not mistake it for a normal debt-clearing sale. Get independent legal advice about continuing liability and the loan terms before agreeing to an unfamiliar arrangement.
Alternatives if selling does not solve the problem
If you want to stay and the payment remains manageable, keeping the home may avoid realizing the shortfall today. That is a choice to evaluate, not a prediction that property values will rise.
If payments are difficult, contact the servicer promptly about repayment arrangements, forbearance, or modification. Availability depends on your loan and finances. Forbearance does not mean the missed amounts are automatically forgiven. See loan modification versus selling for that separate decision.
The CFPB's homeowner assistance guidance recommends contacting the servicer and a HUD-approved housing counselor. You can discuss keeping the home, selling, or other options without assuming a buyer is your only source of help.
Practical steps for a Virginia homeowner
- Collect current payoff statements and identify additional secured debts.
- Get a condition-based listing estimate and any written cash offers.
- Request a settlement estimate that includes known liens and your contractual expenses.
- If there is a gap, ask the servicer about short-sale requirements before promising a closing date.
- Have an attorney review creditor approvals and any proposed deficiency waiver.
- Confirm timing and funds with the settlement professional before closing.
Virginia deed-of-trust terms and applicable law matter; Virginia Code §55.1-320 is part of that legal framework, not a universal debt-forgiveness rule. If foreclosure is already underway, listing or signing an offer does not automatically pause it. Confirm the status directly with the servicer and obtain legal help promptly.
Frequently Asked Questions
Ask for an offer without assuming it clears the debt
Virginia Cash Real Estate can evaluate a Hampton Roads property and provide an as-is offer to compare with your other options. Contact us or call (757) 699-4796. Explain the known payoff gap so the discussion starts with the actual numbers. Any reduced mortgage payoff still requires the appropriate creditor's approval.
General educational information, reviewed October 30, 2026—not legal, tax, or individualized financial advice. Obtain professional advice about your loan, title, and approval documents.